Home Appraisals in Maine: Cost, Process, and What to Expect
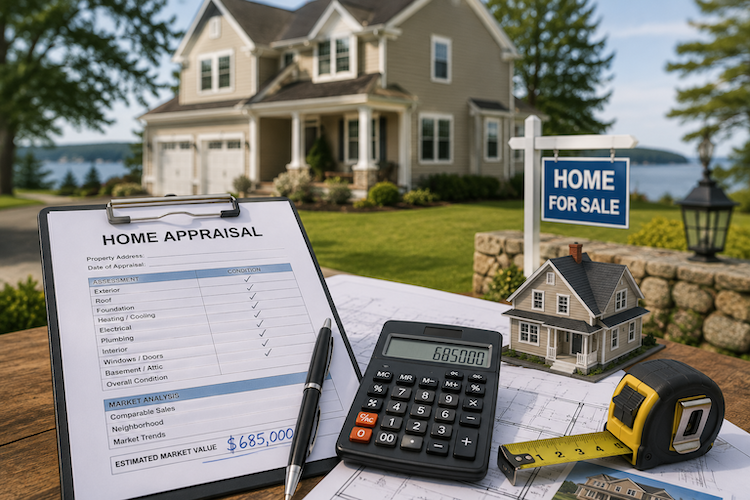
Whether you are buying, selling, refinancing, or settling an estate in Maine, a home appraisal is one of the most important steps in the process. This guide covers what a home appraisal is, what it costs in Maine, how long it takes, when you need one, and how to prepare — so you know exactly what to expect.
Have questions about your home’s value in Southern Maine? Call or text Robert at 207-880-9995.
What Is a Home Appraisal?
A home appraisal is a licensed professional’s independent opinion of a property’s market value at a specific point in time. It is not the same as a home inspection, an automated online estimate, or a comparative market analysis from a real estate agent. It is a formal, documented valuation performed by a state-licensed or certified appraiser and is typically required by mortgage lenders before they will finance a purchase or refinance.
How Much Does a Home Appraisal Cost in Maine?
Home appraisals in Maine are more expensive than the national average. While the national range is roughly $350–$600 for a standard single-family appraisal, Maine appraisals typically run $900–$1,000 for a standard single-family home. Maine ties with Vermont for the highest appraisal fees in New England — compared to $700 in Massachusetts, Connecticut, and Rhode Island.
Several factors can push the cost higher:
- Property size and acreage — larger lots and homes with significant land require more work
- Property type — multi-family, waterfront, or unique properties cost more to appraise
- Loan type — FHA and VA appraisals often cost more than conventional due to additional requirements
- Seasonal access — winter conditions in Maine can affect scheduling and access
- Rural or remote location — fewer comparable sales and longer travel time for the appraiser
The buyer typically pays for the appraisal at closing, though the fee is usually collected upfront when the appraisal is ordered.
How Long Does a Home Appraisal Take in Maine?
From the time your lender orders the appraisal to when the report is delivered, expect one to two weeks in most Southern Maine markets. Here is a general breakdown:
- Appraiser assignment: 24–48 hours after the lender orders through an appraisal management company
- On-site inspection: 30 minutes to a few hours, depending on property size and condition
- Comparable sales research and report writing: several days to a week
Timelines can stretch during busy spring and summer markets in Maine, or when interest rate drops trigger a surge in refinance activity. Waterfront properties, historic homes, and high-value estates may take longer because the appraiser needs to find appropriate comparables — which can be limited in Maine’s coastal and rural markets.
When Do You Need a Home Appraisal in Maine?
Buying a Home
When you finance a home purchase, your lender arranges an appraisal to confirm the property is worth what you agreed to pay. If the home appraises below the purchase price, the lender may not finance the full amount — which means you may need to renegotiate with the seller, cover the difference out of pocket, or exercise your appraisal contingency. Your lender can explain how the appraisal process works for your specific loan type.
Selling a Home
If you are selling, you do not order the appraisal — the buyer’s lender does. However, understanding how appraisals work helps you price your home accurately and prepare for potential negotiations if the appraisal comes in below the agreed price. A pre-listing comparative market analysis can help you anticipate where your home is likely to appraise.
Refinancing
When you refinance your mortgage, your lender may require a new appraisal to confirm current market value before issuing a new loan. Requirements vary by lender and loan type. Some streamline refinance programs (like FHA Streamline or VA IRRRL) may waive the appraisal requirement — your lender can tell you whether one is needed for your situation.
Estate Settlement
When a property owner passes away, an appraisal may be used to establish the fair market value of the home as of a specific date. How that value is used in the estate process depends on the circumstances and applicable law. If you are dealing with an estate that includes real property, consulting an estate attorney is strongly recommended.
Divorce
When a couple with real property divorces, an appraisal may be used to establish current fair market value as part of asset division. How appraisals factor into divorce proceedings varies depending on the situation and jurisdiction. Consult a family law attorney for guidance specific to your circumstances.
Trust, Will, or Estate Planning
If you are placing a property into a trust, updating your will, or doing estate planning, an appraisal may provide a documented value that supports the planning process. Your estate planning attorney can advise you on whether and when an appraisal is appropriate.
Splitting Assets or Partnerships
Any time real property needs to be divided — between business partners, family members, or co-owners — an independent appraisal can provide a neutral starting point for negotiation.
Who Performs a Home Appraisal in Maine?
Home appraisals in Maine must be performed by an appraiser licensed or certified through the Maine Board of Real Estate Appraisers. For purchase and refinance transactions, federal regulations govern how appraisers are selected — your lender works through an appraisal management company to ensure independence. For estate, divorce, trust, and other non-lending purposes, you or your attorney typically engage an independent fee appraiser directly.
What Do Appraisers Look at During a Home Appraisal?
During the on-site visit, the appraiser evaluates the property inside and out. Key factors include:
- Location and neighborhood — proximity to schools, services, and comparable properties
- Lot size and usable land
- Square footage and room count — bedrooms, bathrooms, and overall layout
- Condition and age — structural integrity, roof, foundation, systems (HVAC, plumbing, electrical)
- Updates and improvements — kitchen and bathroom renovations, new windows, energy-efficient upgrades
- Comparable recent sales — the appraiser researches similar homes that have sold nearby within the past several months
In Maine, waterfront access, ocean views, seasonal road access, and well and septic systems are common factors that can significantly affect appraised value.
How to Prepare for a Home Appraisal
You cannot control the appraised value, but you can make sure the appraiser sees your home at its best:
- Complete any minor repairs — leaky faucets, chipped paint, broken fixtures
- Make sure all areas of the home are accessible, including the attic, basement, and garage
- Provide a list of recent improvements with dates and costs if available
- Keep the home clean and uncluttered
- Ensure the appraiser can access the exterior, including the yard, outbuildings, and any waterfront features
What Happens if the Appraisal Comes in Low?
A low appraisal — where the appraised value comes in below the agreed purchase price — is one of the most common challenges in a real estate transaction. If this happens, there are several options:
- Renegotiate the price with the seller to match the appraised value
- The buyer covers the gap by bringing additional cash to closing
- Split the difference — buyer and seller each absorb part of the shortfall
- Challenge the appraisal — your agent can submit additional comparable sales data for the appraiser to review (called a reconsideration of value)
- Walk away if you have an appraisal contingency in your purchase agreement
As your agent, I can help you navigate a low appraisal by providing strong comparable data to support your home’s value and advising on the best path forward.
Appraisal vs. Comparative Market Analysis — What Is the Difference?
A licensed appraisal is a formal document used by lenders and in legal proceedings. A comparative market analysis (CMA) from a real estate agent is a professional opinion used to help price a home for sale or evaluate an offer. Both serve useful purposes, but they are different tools used in different contexts and carry different weight in legal and financial situations.
If you are buying or selling in Southern Maine and want to understand current market conditions, I can provide a free CMA based on current MLS data. For situations requiring a formal appraisal, you will need to engage a licensed appraiser.
Have Questions About Your Home’s Value in Maine?
Call or text Robert Thibodeau at 207-880-9995 or request a free home value consultation today.
First-Time Home Buyer Guide Maine | Home Inspections in Maine | Closing Costs in Maine | Browse Saco Homes | Browse Scarborough Homes
Disclosure: The information on this page is intended for general informational purposes only and does not constitute legal, financial, or investment advice. Market conditions, inventory, and property details change frequently. Appraisal cost estimates are based on publicly available data and may vary. Robert Thibodeau is a licensed real estate Associate Broker with eXp Realty Maine, license BA930057. He is not an attorney, financial advisor, or appraiser. Always consult qualified licensed professionals for guidance specific to your situation. Equal Housing Opportunity. I provide real estate information based on property features, location, pricing, market data, and client goals — not on protected-class characteristics.
 Listing data is derived in whole or in part from the Maine IDX and is for consumers' personal, non commercial use only. Dimensions are approximate and not guaranteed. All data should be independently verified ©2026 Maine Real Estate Information System, Inc. All Rights Reserved.